ARTICLE
The retirement risk no one likes to talk about: you, still here
Living longer is one of the biggest risks in retirement planning. Does your plan assume
Read article
What happens when retirement lasts longer than you planned?
You saved, you stopped working, and your pension and Social Security carried you through. The math was simpler because the timeline was shorter.
That timeline has changed. Many people now live well into their 80s and 90s. Retirement is no longer a decade-long chapter. For many, it will last decades.
The financial industry responded to longer lives by encouraging people to save more and invest better. But saving more doesn’t solve the fundamental problem: nobody knows exactly how long their money needs to last. That uncertainty, the risk of outliving your financial resources, is called longevity risk. And it’s the most underaddressed challenge in retirement planning today.
Retirement used to last ten to fifteen years.
You saved, you stopped working, and your pension and Social Security carried you through. The math was simpler because the timeline was shorter.
That timeline has changed. Many people now live well into their 80s and 90s. Retirement is no longer a decade-long chapter. For many, it will last decades.
The financial industry responded to longer lives by encouraging people to save more and invest better. But saving more doesn’t solve the fundamental problem: nobody knows exactly how long their money needs to last. That uncertainty, the risk of outliving your financial resources, is called longevity risk. And it’s the most underaddressed challenge in retirement planning today.
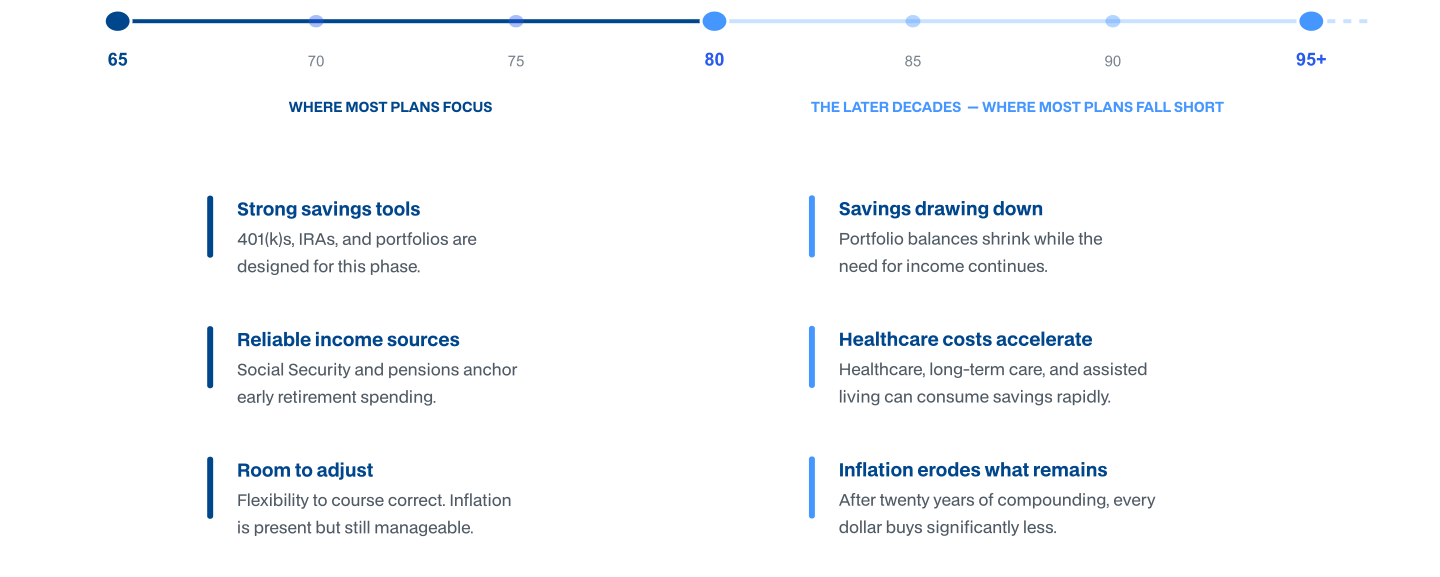
Longevity risk timeline
Where most plans focus.
65
70
75
80
401(k)s, IRAs, and portfolios are designed for this phase.
Social Security and pensions anchor early retirement spending.
Flexibility to course correct. Inflation is present but still manageable.
The later decades — where most plans fall short.
80
85
90
95
Portfolio balances shrink while the need for income continues.
Healthcare, long-term care, and assisted living can consume savings rapidly.
After twenty years of compounding, every dollar buys significantly less.
Retirement can last far longer than most plans assume.
How do you make retirement income last as long as life does? Longevity Finance starts where traditional planning stops, at the point where savings are drawing down, costs are rising, and the tools most people rely on weren’t designed to reach.
| Longevity Finance | Traditional Planning | |
|---|---|---|
| Primary focus | The later decades of retirement, where plans are least likely to have been stress-tested. | Wealth accumulation and early retirement distribution. |
| Starting variable | Time. How long retirement actually lasts drives every decision. | Returns. Portfolio performance drives the planning model. |
| Income design | Planning that accounts for the years when savings are drawing down and costs are rising | Withdrawals drawn from portfolio balances over time. |
| Planning Horizon | Plans for the possibility of reaching 90, 95, or beyond. | Often built around average life expectancy as the endpoint. |
| Spending confidence | Recognizes that uncertainty about lifespan is itself a barrier to spending in retirement. | Portfolio balances that retirees frequently underspend out of fear. |
Two ways to look at retirement planning
Longevity Finance
Primary focus
The later decades of retirement, where plans are least likely to have been stress-tested.
Starting variable
Time. How long retirement actually lasts drives every decision.
Income design
Planning that accounts for the years when savings are drawing down and costs are rising.
Planning Horizon
Plans for the possibility of reaching 90, 95, or beyond.
Spending confidence
Recognizes that uncertainty about lifespan is itself a barrier to spending in retirement.
Traditional Planning
Primary focus
Wealth accumulation and early retirement distribution.
Starting variable
Returns. Portfolio performance drives the planning model.
Income design
Withdrawals drawn from portfolio balances over time.
Planning Horizon
Often built around average life expectancy as the endpoint.
Spending confidence
Portfolio balances that retirees frequently underspend out of fear.
EDUCATION
ARTICLE
Living longer is one of the biggest risks in retirement planning. Does your plan assume
Read article
ARTICLE
Living longer is a blessing, but without financial planning, it can become a burden. Discover
Read article
ARTICLE
Many retirees face a harsh reality, Social Security is projected to fund only 78% of
Read articleIf you’re approaching retirement or already there, and you’ve wondered whether your savings will truly last, you’re not alone. Longevity risk is real, it’s common, and it can be planned for. The best next step is a conversation with a financial advisor who understands the challenge and can help you build an income approach designed for a longer life.